Overview
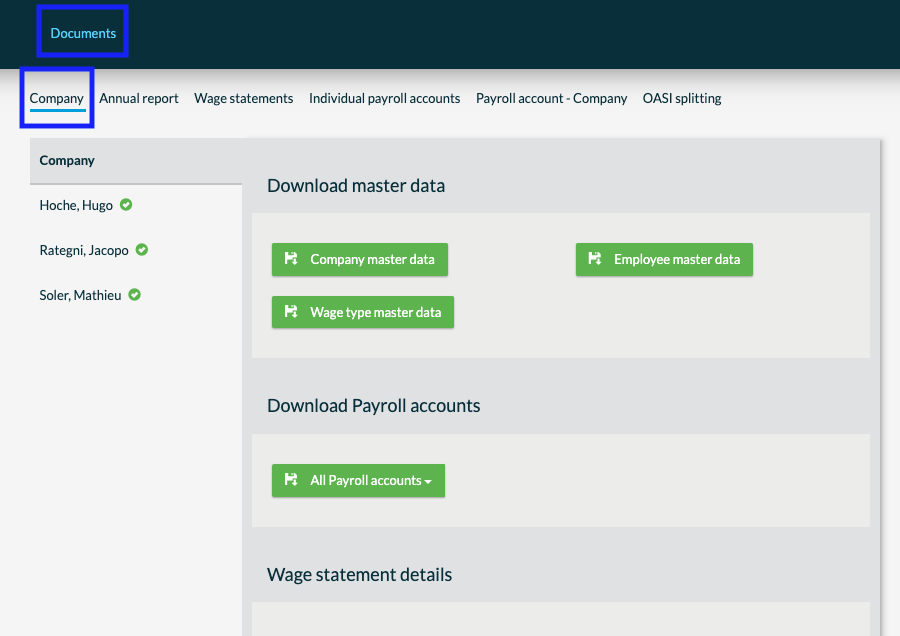
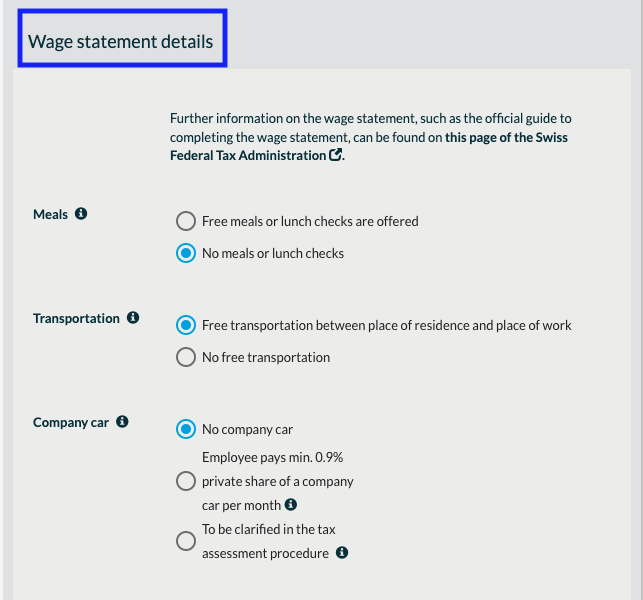
In principle, you can adjust the settings for the wage statement in the tab "Company" - "Wage statement details".
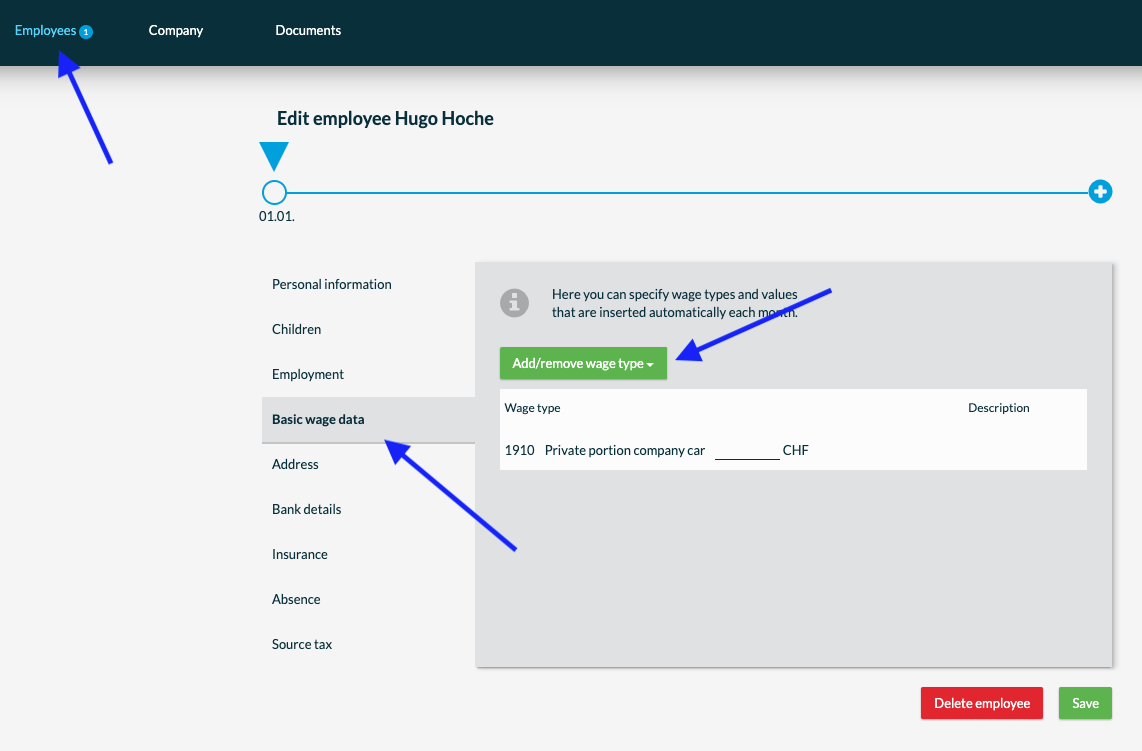
In the tab "Employees" - "Base wage data" you can add the wage type "Private portion company car" and define an amount. This is then listed automatically in the payrolls.
Calculation / Specifications
The treatment of the private portion depends entirely on which accounting method your company has chosen with the Federal Tax Administration (FTA).
The private portion of a company car is always taxable income (own consumption). The question is how this income is taxed:
- For sales tax (actual accounting method)
If your company uses the actual accounting method, the standard rate (sales tax) applies:
• The private portion is taxed at the current standard rate (currently 8.1%).
• The private portion must also be accounted for by owners of sole proprietorships in the form of an input tax adjustment. To do this, make a “manual entry” in bexio under “Accounting.” If you have any questions, please contact your fiduciary.
Example
| Rate | Basis | Amount in CHF |
| Purchase price of the vehicule (excl. VAT) | | | 50000.00 |
| Private share per month | 0.90% | 50000.00 | 450.00 |
However, a minimum of CHF 150.00 must be deducted in all cases. For leasing contracts, the cash sale price (excl. VAT) is used.
This is what a monthly paystub looks like:
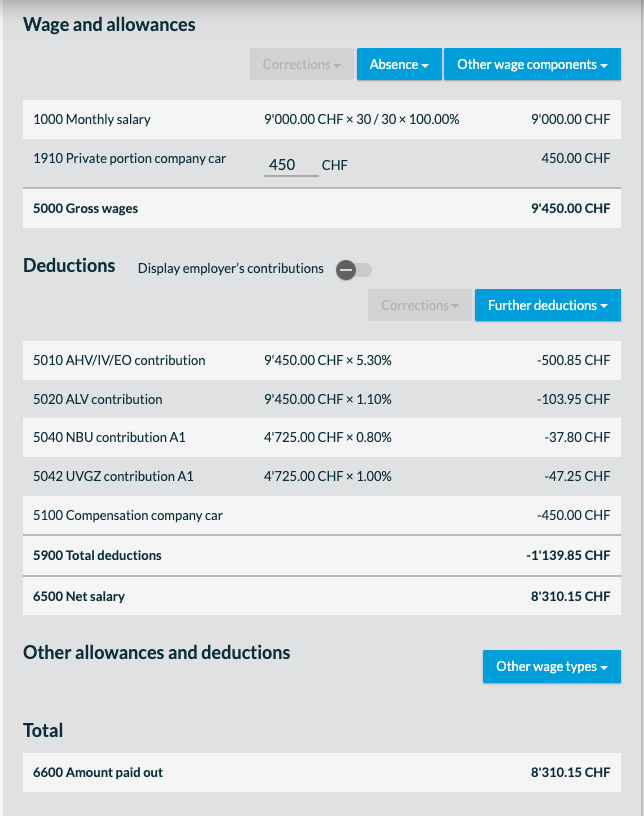
Calculation example based on the above salary statement
| Purchase price of the vehicule: | 50000.00 |
| Private share per montgh: 0.9% (incl. VAT) | 450.00 |
| VAT amount per month: 450.00 / 108.1. x 8.1 | 33.72 |
Note: This rule always applies, regardless of whether there was a right to deduct input tax at the time of purchase (i.e., even with the balance tax rate method).
2. For net tax (net tax rate method)
If your company uses the net tax rate method, the net tax rate applies:
• The private portion is not taxed at the standard rate.
• Instead, the private portion (0.9% of the purchase price) is added to the company's turnover.
• This turnover is then multiplied by your individual net tax rate (e.g. 0.6%) to determine the VAT owed.
• In the case of a sole proprietorship, there is no exchange of services between the owner and the company, and therefore no input tax adjustment is required.
The payroll statement looks exactly the same as with the effective method:
Calculation example according to the above payroll statement
| Purchase price of the vehicule: | 50000.00 |
| Private share per month: 0.9% (incl. VAT): | 450.00 |
| VAT amount per month: 450 / 100 x 06.% | 2.70 |
The amount is listed in section 2.2 of the salary statement. In addition, field F “Free transportation between home and work” must be checked on the salary statement.